Broker operations · Practical guide
Commercial loan broker CRM workflows
A commercial loan broker CRM should keep the borrower relationship connected to the funding process. Start with a contact, record the next action, collect the application and documents, then track each lender submission separately.
By Finance Flow USA
1. Organize the relationship before the deal
Keep prospects, customers, brokers and referral partners organized in your contacts. Use lists to group relevant relationships, and keep communication history and tasks with the contact rather than scattered across separate notes.
For a new inquiry, record what funding the business is seeking and decide who will handle the next conversation. Check for an existing record before creating another one. A task such as “confirm equipment funding needs” is more actionable than a generic reminder to follow up.
2. Review consent and plan follow-up
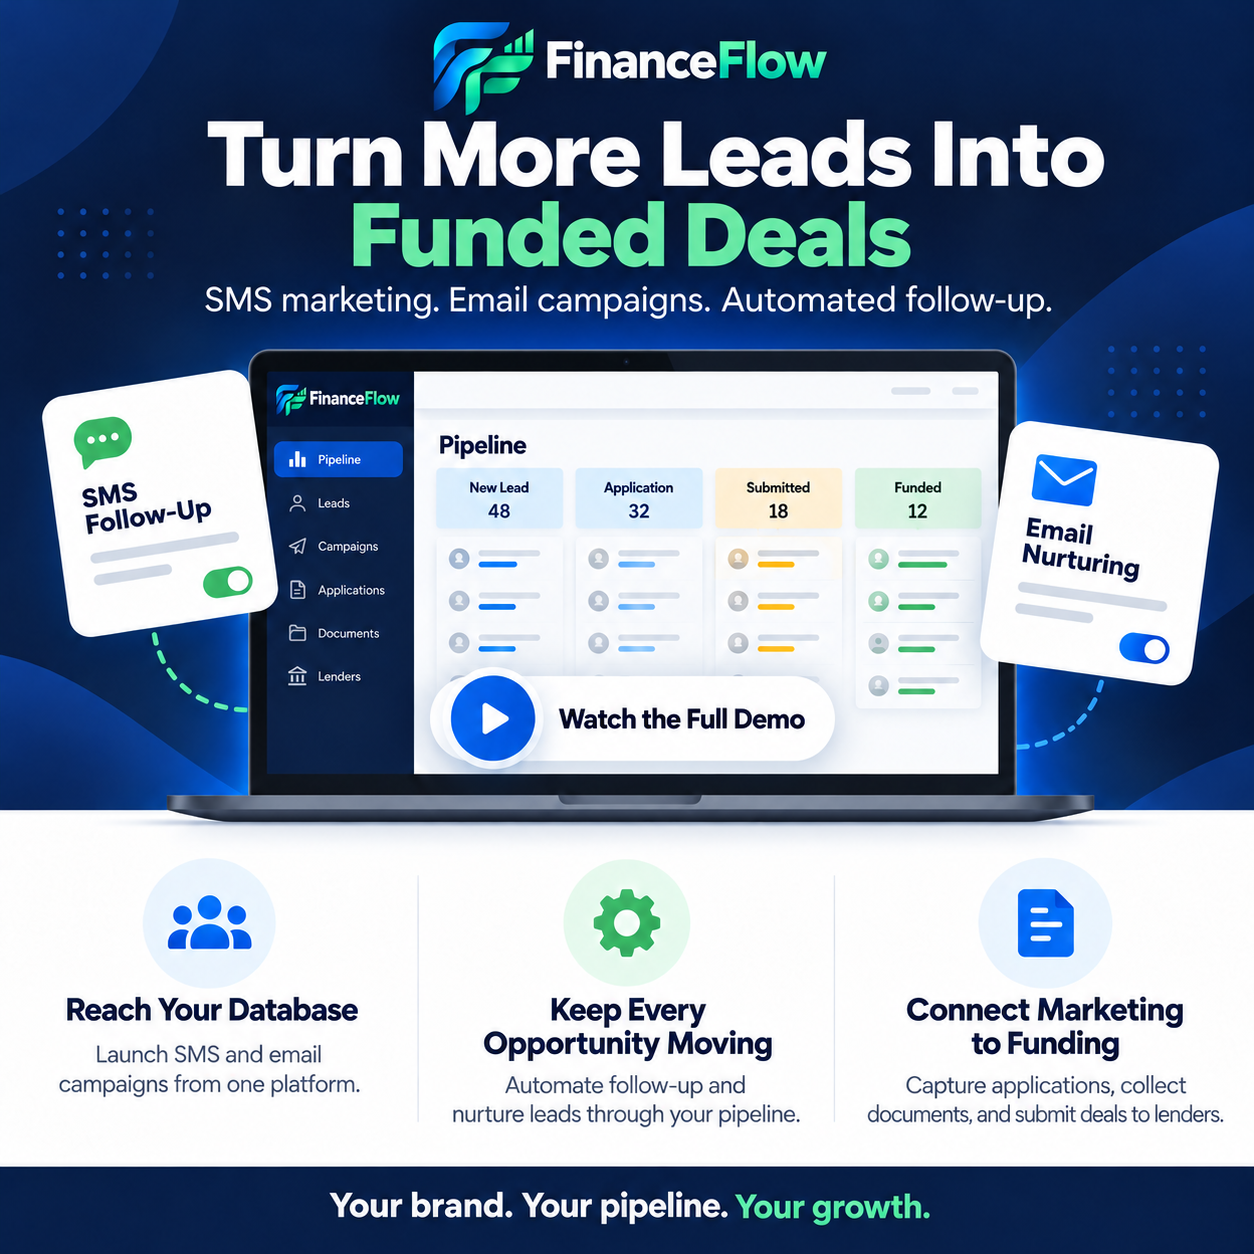
Use SMS and email campaigns for relevant outreach, then connect nurturing to the opportunity’s stage. New inquiries, incomplete applications and outstanding documents need different messages. Keep personal conversations with your team, and use scheduled follow-up for repetitive reminders.
Before starting a campaign, review the audience, message, sending settings and compliance result. FinanceFlowUSA supports opt-out handling and DNC and litigator checks for data added to SMS campaigns. Those checks do not replace your responsibility to obtain appropriate consent or follow applicable messaging rules.
3. Move the borrower into a branded application
Give the business owner a clear application link and explain the next step. FinanceFlowUSA connects branded funding applications and customer portals with your workflow. Keep business details, ownership information and application progress together so the next person reviewing the opportunity has the same context.
For example, after discussing an equipment purchase, ask the borrower to complete the application before requesting a lender review. An application records information; it is not an approval or a funding commitment.
4. Collect and review supporting documents
Keep uploaded documents with the application. Identify what is outstanding, confirm that files are usable and coordinate the handoff before submitting the deal. The documents needed depend on the product and lender; avoid presenting one checklist as a universal requirement.
A practical review asks: Is the business information complete? Are requested statements or invoices attached? Who will contact the borrower about missing information? Stage-based follow-up can support those requests without replacing the reviewer’s judgment.
5. Track lender submissions separately
The borrower’s application and a lender’s submission are related, but they are not the same record. FinanceFlowUSA’s partner channels let lenders manage incoming opportunities and track submission progress independently from the application pipeline.
When an opportunity goes to more than one lender, keep the status and next action for each submission distinct. A request for more information from one lender should not be treated as another lender’s decision. Review the selected submission before changing its status.
6. Review activity and the next action
Use communication and activity history to see what has happened, then assign the next task. Review stalled applications, outstanding documents and submissions awaiting a response. Marketing clicks and visits indicate engagement, not a completed application or a funded deal; keep those outcomes separate when reviewing reports.
A repeatable handoff checklist
- The contact and responsible team member are clear.
- Consent and campaign compliance have been reviewed before outreach.
- The application and requested documents are ready for review.
- Each lender submission has its own current status and next action.
- The borrower knows what happens next, without a promise of approval.
Explore the platform for your workflow
Review the platform and membership options, then discuss your branding, communication and funding process during onboarding.